 Abdul Moeed
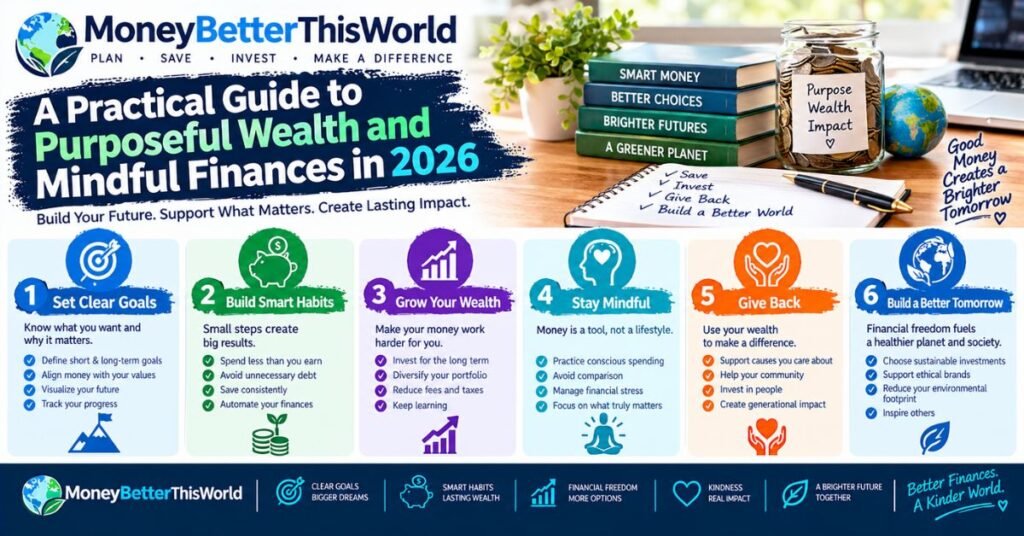
Money means something different to everyone. For some, it means safety. For others, it means freedom. In 2026, a growing idea called Money BetterThisWorld is changing how people think about wealth. It’s not about chasing more money. It’s about using money with a clear purpose.
This guide explains the full Money BetterThisWorld approach. You will learn simple steps for purposeful wealth, mindful finances, and long-term wealth. Every section uses easy English and short sentences. Let’s start.
What Is Money BetterThisWorld?
Money BetterThisWorld is a way of thinking about money. It asks you to use your money on purpose. It is not about buying more things. It is about building financial wellness and a better life.
This idea also focuses on personal finance basics done well. It blends money management with real values. The goal is simple: use money to build a life you actually want, not just a bigger bank account.
The Meaning Behind Money BetterThisWorld
The name says a lot. “Better this world” means your money should help you and the people around you. It’s about purpose-driven finances, not empty spending.
This mindset asks one key question. What is my money actually for? Once you answer that, every money choice gets easier. That’s the heart of wealth with purpose.
Read More: Mastering Your Health: TheSpoonAthletic Guide to Supplement Management
Key Principles of Purposeful Wealth
Purposeful wealth rests on a few simple ideas. It values intention over impulse. It values long-term goals over quick wins. It also values impact, not just income.
These ideas connect to wealth management and financial planning. They also support a strong money mindset. You will see all five core principles explained later in this guide.
Is Money BetterThisWorld a Company, App, or Financial Approach?
Many people ask this question first. Money BetterThisWorld is not a company. It is not an app. You do not need to sign up for anything.
It is simply a financial approach. It is a mindset you can apply today, using tools you already have. Think of it as a lens for better financial decision-making, not a product to buy.
Why Money BetterThisWorld Matters in 2026

Life costs more in 2026. Prices keep rising. Jobs feel less steady than before. This makes financial security harder to find without a clear plan.
The Money BetterThisWorld strategy helps here. It gives people a way to build financial resilience during uncertain times. It also fits a world with more remote work, more digital tools, and more flexible income options.
The Changing Definition of Wealth
Wealth used to mean big houses and fast cars. Today, many people define wealth differently. They want time, freedom, and peace of mind.
| Traditional Wealth | Money BetterThisWorld Wealth |
| Big spending and status | Values-based spending |
| More assets | More freedom and choice |
| Short-term gains | Sustainable wealth |
| Constant comparison | Personal financial priorities |
From Financial Success to Financial Purpose
Financial success used to mean a high salary. Now, more people want meaningful financial goals. A high income means little if it comes with constant stress.
A person earning less but living with a clear plan often feels happier. This is the shift from success alone to real financial well-being. Purpose matters more than the number on a paycheck.
How Modern Financial Habits Are Evolving
Money habits are changing fast. More people freelance. More people bank online. More people use apps to track spending.
These shifts support better smart money habits across the world. They also make modern wealth-building strategies easier to follow, no matter where you live.
The Five Core Principles of Money BetterThisWorld
Five core ideas guide this approach. They work together like steps on a staircase. Each one builds on the last.
These principles are financial awareness, financial responsibility, purpose-driven planning, long-term wealth growth, and positive impact. Let’s look at each one closely.
Financial Awareness
Financial awareness means knowing where your money goes. Many people are surprised by their own spending. Small purchases often add up fast.
Start simple. Track income and expenses every single week. This one habit builds a strong base for every other step in this guide.
Financial Responsibility
Financial responsibility means owning your money choices. It means paying bills on time. It means avoiding blame and focusing on action instead.
This principle supports responsible money management over the long run. Small, steady actions build real trust in your own financial habits.
Purpose-Driven Financial Planning
Goals give your money direction. Without goals, money often disappears on random things. With goals, every dollar has a job to do.
This is where you set financial goals clearly. Buying a home, funding school, or starting a business are all common examples of purpose-driven finances.
Long-Term Wealth Growth
Wealth grows slowly, then quickly. This is the power of compounding. Patience often beats speed in the world of investment planning.
Look at this simple table. It shows how money grows over twenty years at an 8% return.
| Starting Amount | Annual Return | Value After 20 Years |
| $10,000 | 8% | About $46,600 |
| $25,000 | 8% | About $116,500 |
| $50,000 | 8% | About $233,000 |
As one financial teacher often says, “Time in the market beats timing the market.” This quote captures the whole idea behind long-term financial mindset thinking.
Creating Positive Financial Impact
Wealth can help more than just you. It can support family. It can fund causes you care about. This is impact-driven wealth in action.
This final principle turns money into a tool for good. It connects financial success to something bigger than one person’s bank account.
The Psychology of Money and Better Financial Decisions

Money choices are not always logical. Emotions often drive spending more than facts do. Understanding this helps you make better financial decisions.
This section covers three common traps. Each one can quietly damage your financial stability if you don’t notice it early.
Emotional Spending
Stress, boredom, and even joy can trigger spending. This is called emotional spending. It happens to almost everyone at some point.
To avoid emotional spending, try a simple rule. Wait 24 hours before any non-essential purchase. This small pause often stops impulse buys completely.
Read More: Newstown CraigScott Capital: Risks, History & Investor Guide 2026
Lifestyle Inflation
A raise often leads to more spending. This is lifestyle inflation. It quietly eats away at your savings potential.
To control lifestyle inflation, save a fixed share of every raise first. Let the rest support your normal life, not a bigger one.
Social Comparison and Financial Pressure
Social media shows only the highlight reel. It rarely shows debt or financial stress. Comparing your life to online posts is risky.
This pressure hurts healthy relationship with money for many people. Remember, appearances rarely reveal someone’s true financial behavior or bank balance.
How Small Financial Decisions Create Big Results
Consider two people with the same salary. One spends every raise and carries debt. The other saves and invests steadily instead.
After ten years, the saver often has far more wealth. This case study shows how small saving habits create huge results over time. Consistency beats intensity almost every time.
How to Assess Your Current Financial Position
Before building a plan, know where you stand. This step is often skipped, but it matters most. It reveals your true financial health.
This section walks through a full check-up. Think of it like a doctor’s visit, but for your money instead of your body.
Conduct a Personal Financial Audit
A financial audit reviews your full money picture. Look at income, expenses, debts, and savings all at once. This gives a clear, honest snapshot.
Doing this regularly supports strong financial planning habits. Try this every three to six months for the best results.
Track Income and Expenses
You cannot improve what you don’t measure. Write down every dollar earned and spent for one month. Patterns will appear fast.
This habit builds real financial awareness. It also helps you spot ways to reduce unnecessary spending without much effort.
Financial Metrics Worth Monitoring
Numbers tell a clear story. A few key metrics show real financial progress over time.
| Metric | Healthy Target |
| Savings Rate | 20% or higher |
| Emergency Fund | 3 to 6 months of expenses |
| Debt-to-Income Ratio | Below 36% |
| Net Worth | Growing every year |
Identify Financial Strengths and Weaknesses
Once you see the numbers, be honest. What’s working well? What needs fixing? This step guides your next moves clearly.
This process supports better financial priorities. It also helps you monitor your net worth with more confidence going forward.
How to Build a Purposeful Financial Plan
A plan turns goals into real action. Without one, good intentions often fade fast. This section builds your full roadmap.
A strong plan blends holistic financial planning with personal values. It should feel realistic, not overwhelming.
Define Clear Financial Goals
Clear goals guide every good financial plan. Vague goals like “save more” rarely work well. Specific goals work much better.
Try to set financial goals with a number and a date attached. “Save $5,000 by December” beats “save more money” every time.
Short-Term Financial Goals
Short-term goals happen within one year. Common examples include building an emergency fund or paying off one credit card.
These small wins build momentum fast. They also support strong smart money habits early in your journey.
Medium-Term Financial Goals
Medium-term goals take one to five years. Buying property, starting a business, or funding education often fit here.
These goals need steady saving and clear tracking. They bridge the gap between short wins and lifelong dreams.
Long-Term Financial Goals
Long-term goals stretch beyond five years. Retirement and financial independence are classic examples.
These goals need patience and consistent investing. Small monthly actions today create huge results decades from now.
Align Spending With Your Values
Every purchase is a small choice about your life. Before buying, ask three questions. Does this help me? Does it match my goals? Will I still want it next month?
This habit builds conscious spending naturally. It also supports values-based spending across your entire budget.
Create a Realistic Financial Roadmap
A roadmap connects all your goals in order. It shows what to focus on first, second, and third. This avoids feeling overwhelmed.
Review this roadmap often. Life changes, and your personal wealth strategy should change with it.
Budgeting Strategies That Actually Work in 2026
Budgeting is not about restriction. It’s about direction. A good budget shows exactly where your money should go.
This section covers four popular methods. Each one supports budgeting strategies for different personality types.
Zero-Based Budgeting
This method gives every dollar a job. Income minus expenses should equal zero. Nothing gets lost or forgotten.
This works well for detail-focused planners. It builds sharp financial awareness month after month.
Pay-Yourself-First Budgeting
This method treats savings like a bill. Move money to savings before spending on anything else. What’s left covers normal life.
This approach makes it easy to automate savings without much thought. It removes willpower from the equation completely.
Values-Based Budgeting
This method puts more money toward what matters most. It puts less money toward low-value spending. It fits the whole Money BetterThisWorld philosophy perfectly.
This budget style feels personal, not generic. It supports intentional money management in every category.
Read More: Hosted Event PBLGamevent: How Gaming Events Are Organized in 2026
The 50/30/20 Budgeting Rule
This simple rule splits income three ways. Fifty percent covers needs. Thirty percent covers wants. Twenty percent goes to savings and debt.
This rule works well for beginners. It offers structure without too much complexity.
Choosing the Right Budgeting Method
There’s no single perfect method. Choose one that matches your personality and goals. You can also mix methods together.
The best budget is the one you’ll actually follow. Testing a few methods often reveals the right fit fast.
How to Save Money Without Sacrificing Quality of Life
Saving doesn’t require an unhappy life. Smart choices protect your quality of life while still growing your savings.
This section shares real, practical tips. None require extreme sacrifice or constant discomfort.
Practical Ways to Save More Money
Small changes add up over time. Negotiate bills every year. Cancel unused subscriptions. Buy quality items that last longer instead of cheap ones that break fast.
These small habits support saving money without much pain. They quietly free up cash for bigger goals.
Automate Your Savings
Automation removes decision fatigue completely. Set up automatic transfers on payday. The money moves before you even see it.
This single step makes it easy to automate savings long-term. It’s one of the most powerful habits in this entire guide.
Build an Emergency Fund
Life brings surprises. Job loss, medical bills, and car repairs happen to everyone eventually. An emergency fund protects you from these shocks.
Aim to build an emergency fund covering three to six months of expenses. Start small if needed, even fifty dollars a month adds up over time.
Balance Saving With Enjoying Life
Saving too hard can backfire fast. Extreme restriction often leads to burnout and regret. Balance matters just as much as discipline.
Try adding a small “fun money” category to your budget. This supports money and life satisfaction without guilt attached.
Smart Debt Management Strategies
Debt is not automatically bad. How you use it matters most. This section explains how to manage personal debt wisely.
Good debt management protects your credit score. It also protects your peace of mind over the long run.
Understanding Good Debt and Bad Debt
Good debt builds your future. Mortgages and business loans often fall into this group. Bad debt drains your wallet instead, often through high interest rates.
Payday loans and unnecessary credit card debt count as bad debt. Learning this difference is a key personal finance skill.
Debt Snowball vs. Debt Avalanche
Two popular methods exist for paying off debt.
| Method | How It Works | Best For |
| Snowball | Pay smallest debts first | Quick motivation |
| Avalanche | Pay highest interest first | Saving the most money |
Both methods work well. Choose the one that keeps you motivated and consistent.
How to Prioritize Debt Payments
Start by listing every debt with its interest rate. Focus extra payments on the highest priority debt first. Keep minimum payments on everything else.
This structure helps you pay off high-interest debt faster. It also prevents confusion about where to focus next.
Should You Save or Pay Off Debt First?
This is a common and tricky question. Most experts suggest a hybrid approach. Build a small starter emergency fund first, then attack debt aggressively.
Once high-interest debt is gone, shift focus back to saving fully. This balance protects both your safety net and your financial freedom timeline.
Investing for Purposeful Wealth
Saving alone is not enough. Inflation slowly reduces what your money can buy. Investing protects and grows your wealth over time.
This section builds real confidence around investment planning. It also explains how to invest for the long term with less stress.
Why Start Investing Early?
Time is the most powerful investing tool. Starting early lets compounding work harder for you. Even small amounts grow significantly over decades.
Waiting even five years can cost thousands in lost growth. Early action matters more than perfect timing.
Major Investment Categories
Different investments serve different goals. Understanding each type builds stronger wealth building knowledge.
Stocks
Stocks represent ownership in a company. They offer strong growth potential. They also come with higher short-term risk.
Bonds
Bonds offer steady, predictable income. They carry lower risk than stocks. They help balance a portfolio during market swings.
Real Estate
Real estate can generate rental income. It can also grow in value over time. It usually requires more starting capital than other options.
ETFs
ETFs bundle many investments into one purchase. They offer instant diversification. They work well for beginners around the world.
Investing With Small Amounts of Money
You don’t need thousands of dollars to start. Many platforms allow tiny starting investments today. Fractional shares make this even easier.
This removes a common excuse for delay. Anyone can begin building long-term wealth, regardless of income level.
Common Investing Mistakes to Avoid
Even smart people make investing errors. Panic selling during market drops often locks in losses. Chasing trends without research usually ends badly too.
Learning to understand investment risk prevents most of these mistakes. Patience remains the most valuable investing skill of all.
Modern Income Strategies for Building Wealth in 2026
Wealth building needs income growth too. Saving and investing only work with steady cash flow. This section explores real income options for today’s economy.
These strategies fit remote work, freelancing, and traditional jobs equally well. They support income growth from multiple directions.
Increase Your Primary Income
Your main job often holds untapped potential. Learning new skills can lead to raises or promotions. Strong negotiation skills also boost income directly.
This step remains the fastest way to increase your primary income for most people. Small skill investments often pay large returns.
Develop Additional Income Streams
A second income stream adds real security. Freelancing, consulting, and content creation are common examples. These options fit almost any schedule.
Building additional income streams takes time upfront. The extra effort often pays off within a year or two.
Turn Skills Into Additional Income
Everyone has marketable skills already. Writing, teaching, designing, and organizing all have real value. These skills can become paid services fast.
Start small with one client or one project. This approach builds confidence before scaling further.
Understanding the Reality of Passive Income
Passive income sounds effortless, but it rarely starts that way. Most passive income streams require significant upfront work. The “passive” part comes much later.
Setting realistic expectations prevents frustration. True passive income usually takes months or years to build properly.
Technology and Modern Money Management
Technology has transformed personal finance completely. Tools that once felt complicated are now simple and accessible. This section covers the biggest changes shaping 2026.
These tools support wealth management for everyday people, not just professionals. They also improve financial literacy through easy, visual data.
AI-Powered Financial Tools
AI tools now track spending automatically. They spot patterns humans often miss. Some even suggest personalized savings opportunities.
These tools support better financial decision-making with less manual effort. They work quietly in the background every day.
Digital Banking and Money Management
Digital banks offer lower fees than traditional banks. They also offer faster transfers worldwide. This benefits remote workers and global freelancers especially.
These features support smoother money management across borders and currencies.
Financial Automation
Automation extends beyond just savings. Bill payments, investment contributions, and debt payments can all run automatically. This reduces missed payments and late fees.
This system builds build long-term financial stability with minimal daily effort required.
Protecting Your Money With Better Cybersecurity
Digital convenience brings digital risk. Strong passwords and multi-factor authentication matter more than ever. Regular account monitoring catches problems early.
These habits protect your financial security in an increasingly digital world.
Purposeful Wealth and Life Satisfaction
Money affects happiness, but only up to a point. Beyond basic needs, more money brings smaller and smaller benefits. This section explores that balance closely.
Understanding this connection supports true financial well-being, not just a bigger bank account.
Can Money Improve Quality of Life?
Yes, but with limits. Money reduces stress and creates real options. Beyond a certain comfortable point, extra money adds less happiness than expected.
Research on this topic remains widely discussed among economists and psychologists alike.
Money, Freedom, and Personal Priorities
Freedom often matters more than wealth alone. Time freedom, career flexibility, and stronger relationships often bring deeper satisfaction than material goods.
This idea supports a stronger financial freedom mindset overall. It shifts focus from things to experiences and choices.
Avoiding the Endless Wealth Trap
Some people never feel like they have enough. This is the endless wealth trap. Each new goal simply replaces the last one, without ever bringing satisfaction.
Defining your personal “enough” number helps break this pattern. It protects both your mental health and your economic security.
How to Use Wealth to Create Positive Impact
Wealth can serve others, not just yourself. This is where the Money BetterThisWorld purposeful wealth philosophy truly comes alive. Giving and impact become part of the plan.
This section explores practical, realistic ways to create that impact without straining your own finances.
Giving and Charitable Contributions
Giving doesn’t require huge wealth. Even small, regular donations create real impact over time. Consistency matters more than the amount given.
Consider setting aside a small, fixed percentage of income for giving each month.
Supporting Communities and Ethical Businesses
Spending choices support real people and communities. Shopping local and supporting small businesses strengthens local economies directly.
This approach turns everyday spending into a form of responsible investing in your own community.
Investing According to Your Values
Some investors choose companies that match their personal values. This is often called values-aligned investing. It blends financial goals with ethical priorities.
This strategy supports wealth preservation while staying true to personal beliefs.
Using Financial Success for Long-Term Impact
Real wealth often outlives one person. Mentorship, business creation, and family support all extend financial impact for years.
This principle connects financial success to a lasting legacy, not just short-term comfort.
Common Money BetterThisWorld Mistakes to Avoid
Even good intentions can lead to mistakes. This section highlights the most common financial errors people make. Avoiding them saves real time and money.
Each mistake below connects directly back to the core Money BetterThisWorld principles covered earlier.
Spending Without a Financial Plan
Random spending quietly drains progress. Without a plan, money disappears without clear purpose. This mistake undoes even a strong income.
A simple monthly budget review prevents most of this damage completely.
Ignoring Emergency Savings
Skipping an emergency fund feels fine until a crisis hits. Then, debt often becomes the only option available.
Prioritizing this fund protects your entire financial plan from sudden shocks.
Taking on Unnecessary Debt
Not all debt builds a better future. Unnecessary financing for wants, not needs, quietly damages long-term goals.
Pausing before any new debt decision prevents most of these regrettable choices.
Investing Without Understanding Risk
Jumping into investments without research often ends badly. Every investment carries some level of risk attached.
Learning basic risk concepts first protects your money from avoidable losses.
Focusing Only on Income Instead of Overall Financial Health
A high income doesn’t guarantee wealth. Spending habits, debt levels, and savings rates all matter just as much.
True financial health looks at the whole picture, not just one number on a paycheck.
Pros and Cons of the Money BetterThisWorld Approach
Like any approach, this one has strengths and limits. Understanding both sides helps you use it wisely.
This balanced view builds trust and realistic expectations before you start applying these ideas yourself.
Benefits of Purposeful Wealth Management
This approach reduces financial stress significantly. It also creates clearer priorities and stronger long-term outcomes. Many people report a deeper sense of meaning in their financial choices.
Potential Challenges and Limitations
This approach requires consistency over time. It may feel slower than “get rich quick” promises found elsewhere online. It also works best with some basic financial literacy already in place.
Who Can Benefit Most From This Approach?
Beginners overwhelmed by money decisions benefit greatly. High earners feeling unfulfilled also benefit strongly. Really, anyone seeking alignment over pure accumulation fits this approach well.
A 30-Day Money BetterThisWorld Action Plan
Reading about money only goes so far. Action creates real change. This 30-day plan turns every idea in this guide into simple daily steps.
Each week builds on the last, creating steady momentum toward your goals.
Days 1–7: Build Financial Awareness
Track every expense during this week. Calculate your current net worth. Review every subscription you currently pay for.
Days 8–14: Take Control of Your Money
Create your first full budget this week. Cut at least one unnecessary expense. Set up automatic transfers into savings.
Days 15–21: Start Building Wealth
Open or review an investment account this week. Research a few diversified investment options. Set a specific monthly contribution target.
Days 22–30: Optimize Your Financial System
Review your progress from the past three weeks. Adjust any goals that feel unrealistic. Draft a simple twelve-month financial roadmap.
Expert Tips for Staying Consistent With Your Financial Goals
Starting is easy. Staying consistent is harder. This section shares simple habits that keep momentum alive long after day thirty ends.
These tips support lasting change, not just a short burst of motivation.
Review Your Budget Regularly
Set a monthly reminder to review your financial plan. Small adjustments prevent bigger problems later. This habit keeps your budget realistic and current.
Automate Good Financial Habits
Automation removes daily willpower from the equation. Savings, bills, and investments should run automatically wherever possible.
Adjust Your Plan as Your Life Changes
New jobs, moves, or family changes should trigger a plan update. A financial plan should grow and change alongside your life.
Focus on Progress Instead of Perfection
Perfection isn’t the goal here. Small, steady progress always beats occasional perfect months followed by long gaps of nothing.
The Future of Money BetterThisWorld and Purposeful Wealth
The future looks personal and automated. AI-driven planning tools will keep improving. Personalized investment strategies will become more common for everyday investors.
Money BetterThisWorld 2026 trends point toward more automation, paired with more intentional decision-making. As economic uncertainty continues worldwide, purposeful wealth strategies will likely keep growing in popularity.
Frequently Asked Questions
Why Does Money BetterThisWorld Matter in 2026?
Rising costs and economic uncertainty make intentional planning essential. This approach helps people build stability and purpose despite these challenges.
What Are the Core Principles of Money BetterThisWorld?
The five principles are financial awareness, financial responsibility, purpose-driven planning, long-term wealth growth, and positive impact.
How Can Money BetterThisWorld Improve Financial Habits?
It builds awareness first, then alignment. This combination naturally leads to smarter, more intentional daily money choices.
Is Money BetterThisWorld a Financial Strategy?
It’s a philosophy that shapes strategy, not a rigid strategy itself. It guides decisions rather than dictating exact rules.
How Can I Start Practicing Purposeful Wealth?
Start with the 30-day action plan outlined earlier in this guide. Small, consistent steps build real momentum fast.
Can Money BetterThisWorld Help With Long-Term Wealth Building?
Yes. These principles compound over time, much like investments do. Small habits today create significant results years down the road.
Conclusion
Money BetterThisWorld offers a simple but powerful shift. It moves focus from endless accumulation toward real purpose. It blends financial awareness, financial responsibility, growth, and impact into one clear approach.
This journey doesn’t require perfection or a huge income. It only requires one honest decision today. Pick one step from this guide, whether tracking expenses or opening an investment account, and start now. Every intentional choice moves you closer to true financial freedom and a life built with real purpose.